Principal
State the exact dollar amount being loaned and whether advances or additional draws are permitted, with clear rounding rules.
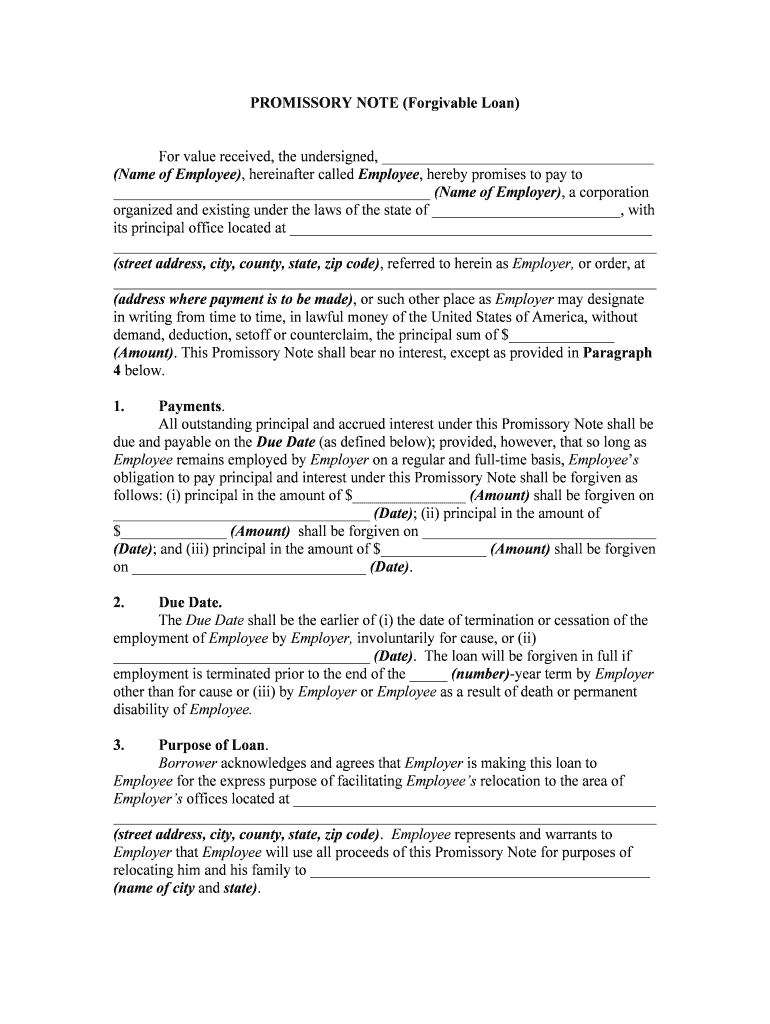
A well-drafted promissory note creates a clear, enforceable record of the loan, defines repayment and remedies, and supports collection or secured-credit actions. It reduces ambiguity about terms and can speed dispute resolution.

Promissory notes are used by a range of parties from individuals to businesses; the document should match the complexity and risk of the transaction.
Choose the level of formality (notarization, attorney review, security filings) based on loan size, collateral, and regulatory considerations.
State the exact dollar amount being loaned and whether advances or additional draws are permitted, with clear rounding rules.
Specify rate type (fixed or variable), calculation method (simple vs. compound), payment frequency, and any maximum or usury protections.
Set payment schedule, installment amounts, payment method, prepayment terms, and application of payments to principal/interest.
Define events of default, grace periods, acceleration rights, late fees, and permitted cure periods for the borrower.
If secured, reference collateral, attachment steps, and cross-reference any UCC-1 financing statement filings and requirements.
Name the state law that will govern interpretation and dispute resolution, and any venue or jurisdiction preferences.
| Field | Configuration |
|---|---|
| Signature | Required; signer email + timestamp capture |
| Date Field | Auto-fill MM/DD/YYYY on signer action |
| Initials | Optional; use to track page-level consent |
| Attachment | Allow upload of IDs or collateral docs |
Choose a platform that captures intent, consent, attribution, and retention to satisfy ESIGN/UETA enforceability standards.
Ensure the provider supports required integrations and compliance controls for your industry and jurisdiction.
Date specified in the repayment schedule
Follow contract grace period before formal notice
Occurs on contract-specified default and cure lapse
Typically 3–6 years depending on state law
Keep executed note for the life of the loan plus recommended period
Save the executed note as PDF/A for archival and as native DOCX for editing or redaction history when needed.
Attach loan applications, ID copies, payment schedules, and UCC-1 filings to the executed note for a complete record.
Retain an immutable audit record showing signer identity, timestamps, IP addresses, and any authentication method used.
Store encrypted copies offsite or in compliant cloud storage with access controls and retention policies.
A lender-side representative responsible for reviewing borrower credit, confirming terms, and ensuring the promissory note and any security documents are executed and filed correctly.
The individual or entity legally obligated to repay the debt; must provide accurate identity information and sign in the required format to bind the obligation.
Ensure the final, unsigned document is complete before presenting for signing.
Signer presents government-issued ID and any additional credentials.
If witnesses required, have them observe signature and sign where indicated.
Notary completes acknowledgement or jurat as appropriate.
If used, record the A/V session per state rules and retain the recording.
Include the notary certificate and any witness affidavits with the note copy.
If secured, file UCC-1 after signature to perfect the lien.
Provide executed copies to all parties and retain master record.
| signNow | DocuSign | Adobe Sign | PandaDoc | HelloSign | |
|---|---|---|---|---|---|
| Starting Price | $8/user/mo | $15/user/mo | $14/user/mo | $19/user/mo | $15/user/mo |
| Free Trial | 7-day trial | Varies | Varies | Varies | Varies |
| Bulk Send | Yes | Yes | Yes | Yes | No |
| Audit Trail | Yes | Yes | Yes | Yes | Yes |
| HIPAA Compliant | Yes | Yes | Yes | No | No |
A small-business owner lends capital to a vendor with a 12-month note and fixed monthly payments.
A homeowner finances a buyer with a multi-year note and balloon payment at maturity.