Establishing secure connection…Loading editor…Preparing document…

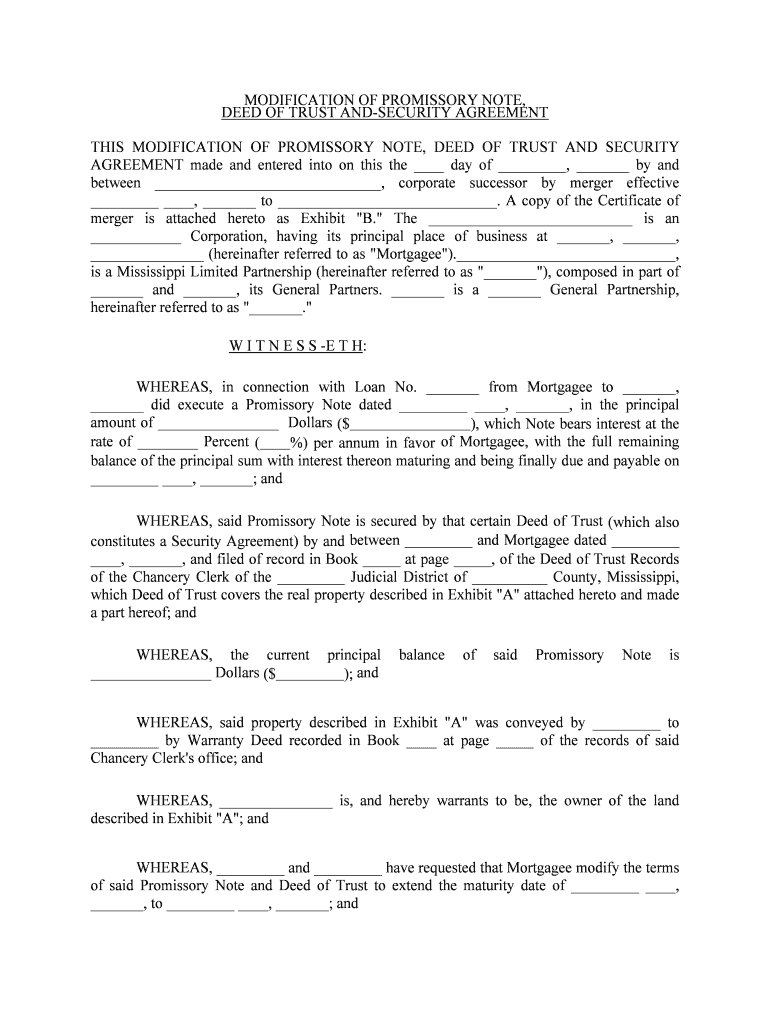
Modification of Promissory Note and Deed of Trust

This template is fully customizable. Edit the text, fill out the fields, and send it for signature. Give it a try!
Modification of Promissory Note and Deed of Trust

What this Modification of Promissory Note and Deed of Trust Is

A Modification of Promissory Note and Deed of Trust is a written amendment that changes terms of an existing loan agreement and the secured deed of trust without creating a new loan. Common uses include adjusting interest rate, extending maturity, changing payment schedules, or curing defaults while preserving the original lien priority. The document identifies the original note and deed, specifies which provisions are changed, and confirms remaining terms remain in force. Properly executed amendments protect borrower and lender expectations and enable county recorders to reflect changed terms for third parties.

Why You Might Use a Modification Instead of a New Loan

Modifying the existing note and deed can avoid re-underwriting, preserve lien priority, reduce closing costs, and provide a clear, enforceable record of changed loan terms under the original security instrument.

Why You Might Use a Modification Instead of a New Loan

Who Commonly Prepares and Signs These Modifications

Parties often engage counsel for complex changes; recording the instrument with the county recorder is usually required to put third parties on notice.

  • Loan Servicers and Banks — Draft and execute modifications to manage loan workouts, interest rate changes, or maturity extensions while maintaining lien priority.
  • Borrowers/Homeowners — Sign to accept new payment terms or amendments that prevent foreclosure or allow refinancing exceptions.
  • Title Companies and Recording Agents — Verify form completeness and submit modifications for recording to reflect the amended lien on public records.

Six Core Parts of a Professional Modification

A compliant amendment includes specific references to the original instruments, precise amendment language, signature blocks, notarization where required, recording instructions, and an integration/ratification clause confirming unchanged terms remain effective.

Reference

Full citation of original promissory note and deed of trust by date, book/page or instrument number, parties, and county of record.
Amendment Terms

Clear, unambiguous language stating which loan provisions are modified (rate, term, payment, maturity, or acceleration clauses).

Consideration

Statement of consideration or rationale (forbearance, fee, interest concession) to support enforceability under contract law.

Signatures

Execution blocks for borrower, lender, and any required spouse/co-signer with printed names, titles where applicable, and dates.

Notary Acknowledgement

State-specific notary block for acknowledgment or jurat; remote online notarization (RON) language if used.

Recording Directive

Instruction describing where the modification should be recorded, including county recorder name and mailing or return address.

Step-by-Step: Completing the Modification

Follow these steps to create, execute, and record a valid modification of the promissory note and deed of trust.

  • 01
    1. Identify Original Instruments: Locate recorded deed and note references before drafting amendments.
  • 02
    2. Draft Clear Amendments: Use precise language changing only intended clauses and quoting existing text when replacing provisions.
  • 03
    3. Obtain Required Approvals: Secure lender committee, investor, or servicer sign-off where loan servicing agreements require consent.
  • 04
    4. Execute and Notarize: Sign in presence of a notary or use permitted RON procedures; include notary block per state law.

How Execution and Recording Typically Flow

Execution and recording follow a predictable workflow from creation to public filing; understanding each step reduces errors and processing delays.

  • Draft: Prepare amendment referencing original documents and specifying changes.
  • Review: Counsel and title review identify conflicts and recording implications.
  • Sign: Parties sign before notary or via authorized e-notary process.
  • Record: Submit to county recorder with recording fees and return instructions.

Digital Workflow Settings for Online Completion and eSigning

Configure the eSignature workflow to capture identity, notarization, routing, and a tamper-evident audit trail before recording.

Field Configuration
Signer Authentication Email + SMS code or knowledge-based authentication where required
Notary Support Enable RON session recording and notary role if remote notarization will be used
Sequential Routing Set signer order so lender signs after borrower or vice versa as contract requires
Audit Trail Capture IP, timestamp, certificate of completion, and event log

Technical Considerations for eSigning and eNotarization

Verify that the platform can produce a tamper-evident signed PDF, a downloadable audit trail, and any required notarization recording for long-term retention.

  • File Formats: PDF/A or PDF with embedded metadata to satisfy county recorder and title company requirements
  • Integrations: Connectors for CRM or title systems (Salesforce, NetSuite, Box) reduce manual entry and reconciliation
  • Security: TLS in transit and AES-256 at rest to protect loan and personal data

Timelines and Typical Processing Expectations

Understand both internal approval deadlines and external recording timelines to prevent unintended defaults or title gaps.

Internal Approval Window:

Allow 3–14 business days for lender or investor sign-off depending on complexity.

Notarization Scheduling:

Book local notary or RON session at least 2–7 business days before target execution.

County Recording Time:

Recording can take 1–4 weeks depending on county workload and whether physical submission is required.

Title Reissue/Endorsement:

Title updates or endorsements may take an additional 3–10 business days.

Effective Date vs Recorded Date:

Amendment may be effective on execution date but third-party notice depends on recording date.

Key Milestones from Draft to Recorded Amendment

A typical modification lifecycle includes preparation, approvals, execution, and public recording; track each milestone to avoid lapse or dispute.

01

Preparation

Draft amendment and include original instrument references.

02

Title Review

Confirm no intervening liens or defects that prevent recording.

03

Execution

Signers execute with required notarization or RON session recorded.

04

Recording

Submit instrument and fees to the county recorder and confirm return of recorded copy.

Common Pitfalls to Avoid

  • Incomplete reference to the original deed or note, making the amendment unlinked in title searches.
  • Using vague amendment language that does not specify numeric terms or deadlines.
  • Failing to obtain required lender/investor approvals, which can render the modification unenforceable.
  • Neglecting state-specific notarization or witness requirements before recording.

Risks and Legal Consequences of an Incorrect Modification

Loss of Priority: An improperly recorded or referenced modification can jeopardize lien priority and expose lender to junior liens.
Foreclosure Exposure: Failure to document defaults or rescind acceleration correctly can accelerate default remedies and foreclosure.
Title Insurance Problems: Title underwriters may refuse coverage or issue exceptions if amendments are unclear or unrecorded.
Tax and Reporting: Incorrect modification terms may affect tax treatment of interest or debt forgiveness reporting.
Regulatory Noncompliance: Loans subject to federal/state consumer lending rules may require specific disclosures; omissions can lead to penalties.
Notarization Defects: Invalid notarization or improper RON procedure can render the amendment void for third-party record purposes.

Security and Compliance Considerations

Encryption: TLS 1.2/1.3 in transit; AES-256 at rest
Audit Trail: Timestamped events, IP addresses, and signer attribution
HIPAA: BAA required when health information is present
ESIGN/UETA: E-signatures recognized under 15 U.S.C. ch. 96 and UETA
21 CFR Part 11: Available controls for FDA-regulated records
Access Controls: Role-based permissions and SSO/SAML options

Selected eSignature Pricing and Capability Comparison

Compare entry-level pricing and a few high-level features for common eSignature vendors; signNow is listed first for direct comparison without implying endorsement.

signNow DocuSign Adobe Sign PandaDoc HelloSign
Starting Price $8/user/mo $15/user/mo $14/user/mo $19/user/mo $15/user/mo
Free Trial 7-day free trial Varies by plan Varies by plan Varies by plan Varies by plan
Bulk Send Yes (Business Premium) Varies by plan Varies by plan Varies by plan Varies by plan
Audit Trail Yes Yes Yes Yes Yes
HIPAA Compliant Yes (BAA available) Varies by plan Varies by plan Varies by plan Varies by plan

Frequently Asked Questions About Modifying a Promissory Note and Deed of Trust

Answers to common legal and practical questions about validity, notarization, recording, and electronic execution of modifications.


Need help? Contact support

be ready to get more
Join over 28 million airSlate SignNow users