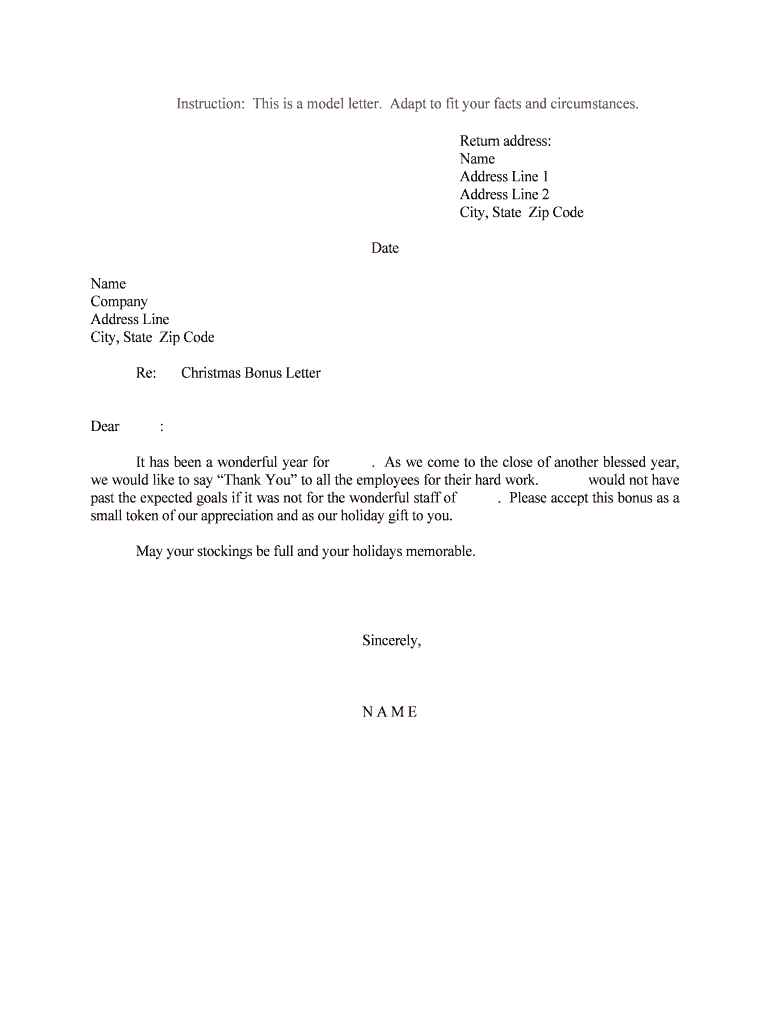
Christmas Bonus Letter
What a Christmas Bonus Letter Is and When It’s Used
Why Issuing a Clear Christmas Bonus Letter Matters
A written letter reduces ambiguity about eligibility, withholding, and timing, protects both parties, and creates an auditable record for payroll and tax reporting. It aids consistent application of company policy and supports accurate year-end reporting.
Who Typically Prepares and Receives This Letter
Human resources, payroll administrators, and business owners usually prepare the letter; employees and contractors are the recipients.
- HR departments managing company-wide bonus programs and documentation.
- Payroll teams that need instructions for tax withholding and reporting.
- Small business owners issuing discretionary payments to staff or contractors.
Who Signs or Approves the Letter
HR Manager
The HR manager or director typically drafts and approves the letter, ensuring it aligns with bonus policy and that payroll receives correct withholding instructions; HR also retains a copy for personnel records and audit purposes.
Finance Lead
A finance or payroll lead reviews payment timing and budget impact, confirms tax withholding approach, and authorizes the payment so accounting entries and bank transfers match the letter terms.
Step-by-Step: Preparing and Sending a Christmas Bonus Letter
-
01Draft Letter: Populate employee name, amount, payment date, tax treatment, and conditions.
-
02Obtain Approval: Finance and HR sign or approve using designated authority workflows.
-
03Deliver Notice: Send via secure email, internal portal, or signed paper, retaining proof of delivery.
-
04Record Payment: Ensure payroll posts the bonus with correct withholding and retains documentation.
Typical Process Flow for Electronic Delivery and Tracking
-
Create Document: Upload letter template and add fillable fields for recipient and amount.
-
Apply Signatures: Assign signer roles and capture signatures with timestamped audit data.
-
Notify Payroll: Push approved instruction to payroll or export CSV for batch processing.
-
Archive Record: Store signed copy in secure records system with retention metadata.
Recommended Digital Workflow Settings
| Field | Configuration |
|---|---|
| Employee Name | Required; auto-populate from HRIS |
| Bonus Amount | Required; numeric validation and currency format |
| Approver | Role-based approval; two-step for amounts above threshold |
| Delivery Method | Email link or direct download; record delivery status |
Platform and File Requirements for eSubmission
Choose a platform that supports signed PDF and DOCX uploads, audit trails, and role-based approvals for payroll-related notices.
- Accepted Formats: PDF, DOCX, and HTML
- Authentication: Email or SMS code; optional KBA
- Integrations: HRIS and payroll connectors
Ensure the platform can export signed records to HR and finance systems, retain audit logs, and meet applicable compliance requirements such as ESIGN, UETA, and HIPAA where relevant.
Key Timing and Reporting Deadlines to Keep in Mind
Payment Cutoff:
Set payroll submission deadlines at least one business day before the payment date to ensure timely processing.
Employee Notice:
Provide written notice to employees ahead of payment to confirm conditions and tax treatment.
W-2 Reporting:
Bonuses are reported on W-2 and must be included in year-end wage totals (employee W-2 provided by Jan 31).
Tax Withholding:
Confirm supplemental withholding method before payroll run to avoid underwithholding and potential penalties.
Record Retention:
Retain the signed letter with payroll records for the applicable retention period for tax and audit purposes.
Milestones from Decision to Payment
Plan and Budget
Determine eligibility, amount, and budget impact for the bonus.
Approval
Obtain required sign-offs from finance and HR leadership.
Employee Notification
Issue the Christmas Bonus Letter and capture acknowledgement.
Payroll Execution
Process payment on scheduled date and record withholding entries.
How a Christmas Bonus Letter Differs from Other Bonus Documents
| Document Type | Christmas Bonus Letter | Bonus Agreement |
|---|---|---|
| Legal Form | notice only | contractual promise |
| Audience | individual employee | employee or group |
| Payroll Impact | one-time instruction | may create recurring obligation |
| Signatures | optional but recommended | required for enforceability |
Typical eSignature Vendor Pricing and Capability Snapshot
| signNow | DocuSign | Adobe Sign | PandaDoc | HelloSign | |
|---|---|---|---|---|---|
| Starting Price | $8/user/mo | $15/user/mo | $14/user/mo | $19/user/mo | $15/user/mo |
| Free Trial | 7-day free trial | Varies by plan | Varies by plan | Varies by plan | Varies by plan |
| Bulk Send | Yes (Premium) | Yes | Yes | Yes | Varies by plan |
| Audit Trail | Yes | Yes | Yes | Yes | Yes |
| HIPAA Compliant | Yes (BAA) | Varies by plan | Varies by plan | Varies by plan | Varies by plan |
| Envelope Cap | No cap | 100 envelopes/user/year | Varies by plan | Varies by plan | Varies by plan |
Practical Tips to Avoid Errors and Delays
Example Scenarios for Christmas Bonus Letters
HR Department Example
A mid-size company issues a standardized letter to all eligible staff explaining amount and payment date.
- The letter clarifies tax treatment and eligibility.
- HR retains a signed copy in personnel files and sends a payroll instruction to accounting to ensure consistent posting and reporting.
Small Business Owner Example
A small business owner sends a personalized letter to key employees with a fixed dollar bonus and conditions.
- The letter requests employee acknowledgement.
- The signed document is stored with payroll records and the owner confirms tax withholding with their payroll provider before payment.
Potential Risks and Consequences of Errors
Common Preparation Mistakes to Avoid
- Failing to specify whether the bonus is discretionary or guaranteed, which can create contractual expectations or disputes about continued payments.
- Using vague payment timing like 'before year-end' without a specific date, resulting in missed payroll cutoffs and incorrect tax year reporting.
- Neglecting to coordinate with payroll on withholding method, which can create underwithholding and require corrective payroll runs.
- Not preserving proof of delivery or signature for electronically delivered letters, complicating audit trails and legal defenses.
Frequently Asked Questions About Christmas Bonus Letters
-
Can this letter be e-signed?
Yes. Electronic signatures are generally enforceable under the ESIGN Act (15 U.S.C. ch. 96) and UETA where adopted, provided the signing shows intent, consent, attribution, and retention. Verify consumer disclosure obligations for consumer-facing financial or healthcare matters.
-
Do bonuses need to be reported for tax purposes?
Yes. Cash bonuses are taxable wages and must be included on the employee’s W-2 for the year paid, with appropriate payroll tax withholding and employer tax deposits as required.
-
What if the amount is wrong?
Correct the error promptly by issuing an amended payroll entry and an updated signed letter if necessary; document approvals for adjustments and notify the employee in writing.
-
Is notarization required?
Notarization is not typical for bonus letters. Only use notarization if a jurisdiction or internal policy specifically requires it for your payment authority documentation.
-
How do I revoke or change the letter?
Issue a clear written amendment or revocation signed by the same authority that issued the original, and coordinate with payroll to reverse or adjust payments before they are processed.
-
Where should signed letters be stored?
Store signed copies with payroll and personnel records according to retention policies; ensure secure access controls, encrypted storage, and retention schedules aligned with IRS and industry requirements.